3.0%Stable
Global GDP Growth
IMF holds its 2026 forecast steady; global business activity opened H2 on solid ground.
An AI supercycle, resilient trade and a global easing cycle are rewriting the map of growth — continent by continent, sector by sector.
Geopolitical friction and sticky inflation were supposed to stall the world economy in the second half of 2026. Instead, the IMF now pegs global growth at a steady 3.0%, foreign direct investment jumped 42% in the first quarter, and the deepest capital-expenditure boom in a generation is compounding across chips, grids and clean power. This edition travels all seven continental boards to find where the momentum is real — and why the smartest money is already positioned.
Five signals that define the second half of 2026 — from the AI capex boom to the quiet easing of global financial conditions.
IMF holds its 2026 forecast steady; global business activity opened H2 on solid ground.
Cross-border investment roared back, led by electronics and the semiconductor supply chain.
AI-driven capital spending by the largest tech groups — many lifting capex over 80% — keeps America's expansion intact.
The IMF raised its view as green transition, digitalization and computing power compound into "Opportunity 2.0".
From Hong Kong to Bogotá, Helsinki to Sydney, every continental board of the world economy is carrying its own version of the same story: structural tailwinds are winning.
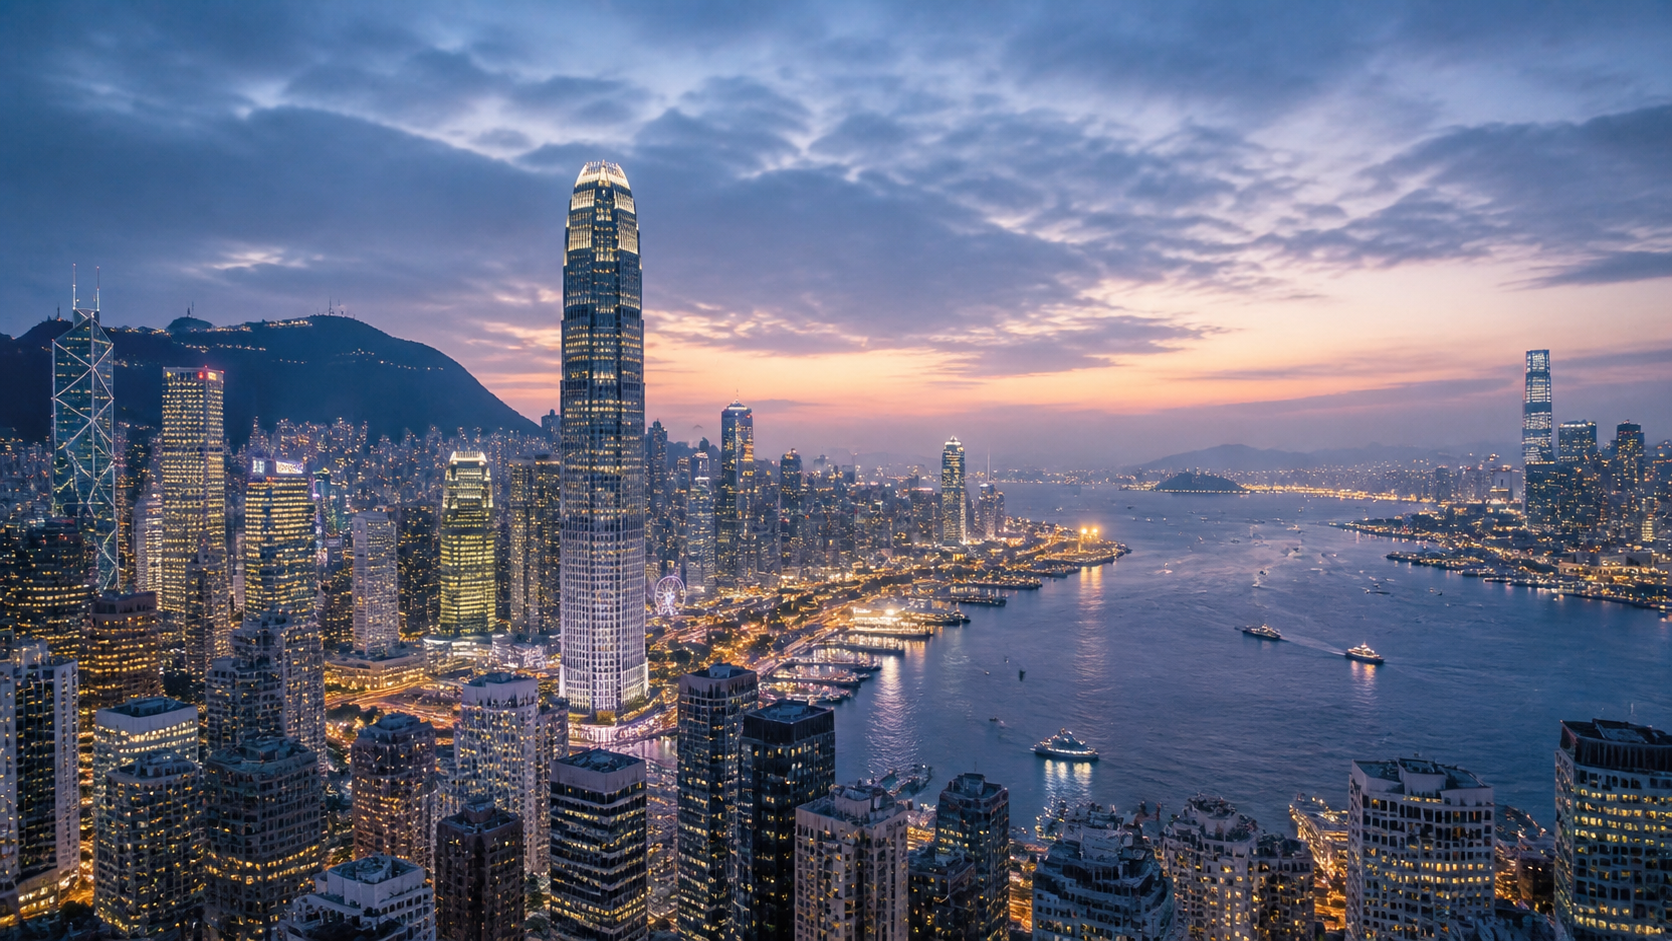
The world's growth anchor shifts from low-cost scale to innovation depth.
Asia's anchor economy is the headline. The IMF lifted its 2026 growth projection to 4.6% as it leaps from the low-cost "1.0 era" into "Opportunity 2.0" — a model built on green transition, digitalization and intelligent manufacturing. The season's global trade-in-services fair alone produced more than 1,200 signed outcomes, new-type energy storage is on track to reach 300 GW of scale by 2030, and the region's computing power is expected to hold roughly 30% of the global total by the decade's end — keeping Asia the core stabilizing anchor of global growth.
Hong Kong turns that growth into global access. As the region's international financial center, it channels worldwide capital into Asian listings, treasury flows and green-finance structures — the connector between this expansion and the world's balance sheets. Around it, India sustains a domestic-demand-led expansion with striking resilience, and the ASEAN bloc — Indonesia, Malaysia and their neighbors — is absorbing supply-chain relocation and a rising technology-trade cycle, becoming one of the hottest destinations for foreign direct investment on the planet.
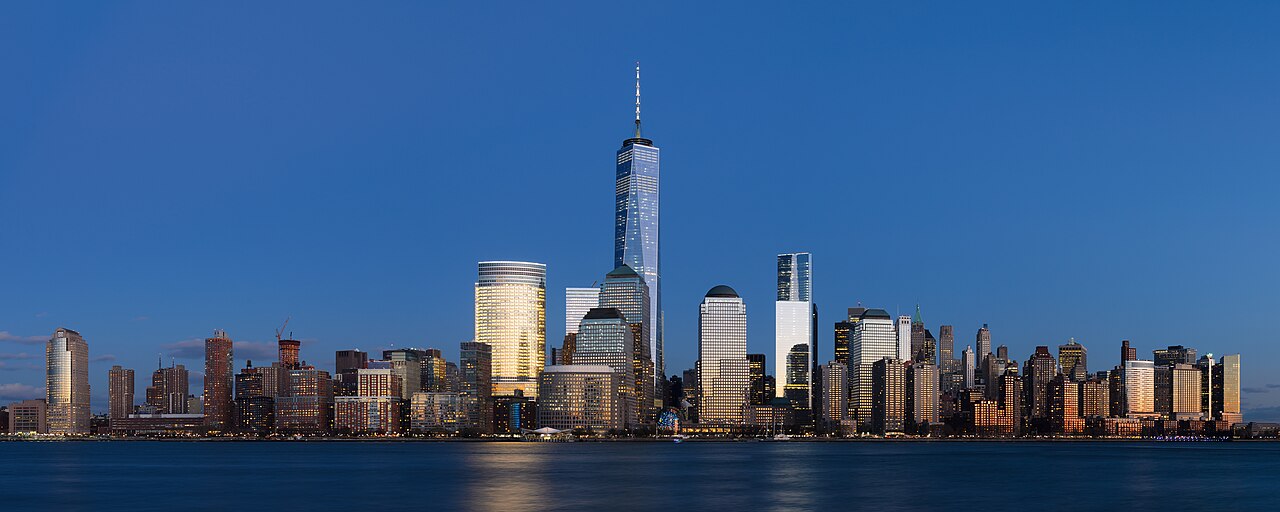
America's growth is no longer consumer-led first — it is machine-led.
Despite macro crosscurrents, the US expansion remains remarkably resilient, with the IMF holding its 2026 GDP forecast at 2.3%. The engine is an extraordinarily strong AI capital-expenditure cycle: the four largest hyperscalers are lifting capex by more than 80%, funneling money into advanced packaging, high-speed interconnects and the server supply chain.
Goldman Sachs and peers argue that, combined with tax incentives and loosening financial conditions, that momentum could still surprise to the upside — making North America the single deepest pool of private investment in the world this cycle.
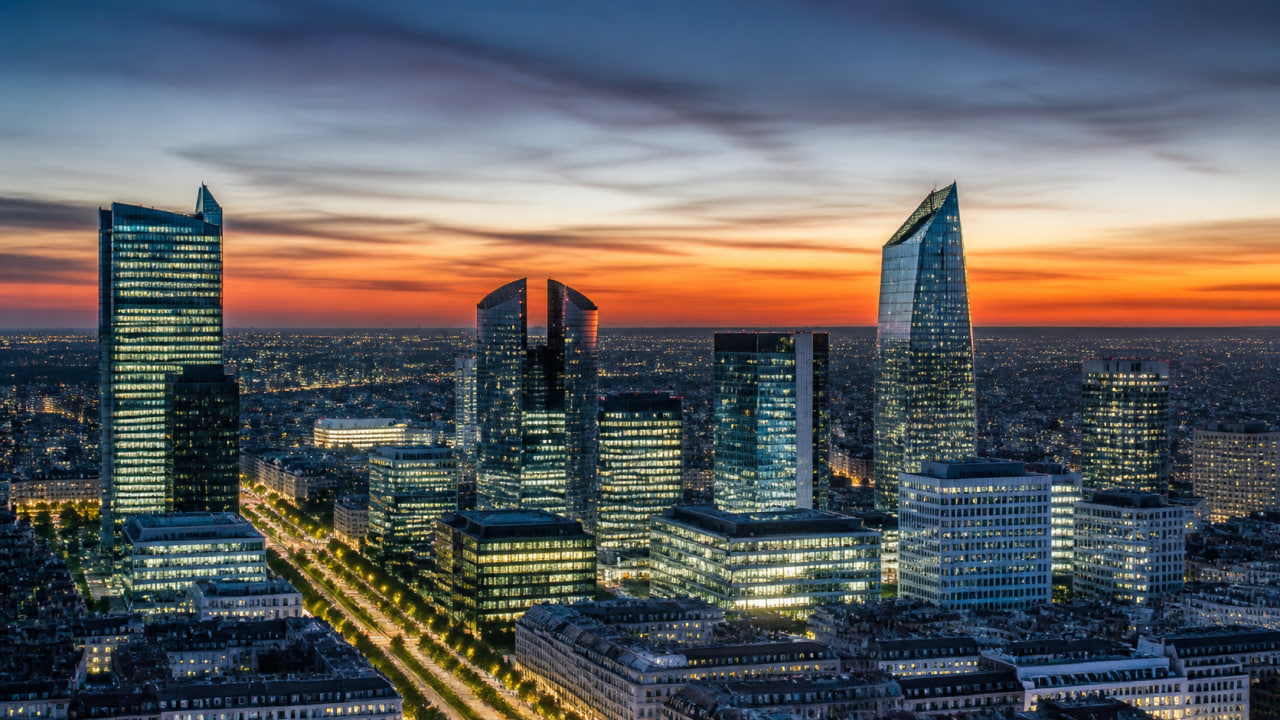
The continent everyone wrote off is quietly beating its numbers.
S&P Global raised its 2026 real-GDP forecast for the euro area and Western Europe by 0.4 percentage points, crediting a second-quarter rebound in exports and domestic demand that outperformed every expectation. In the Nordics, central-bank reports point to higher growth and lower unemployment at the same time — a combination rarely on offer.
The surprise package is Germany: net exports ran so hot that actual GDP growth landed at almost twice what forecasters had priced in, pulling the Central European manufacturing chain back toward expansion and re-igniting the continent's industrial core.
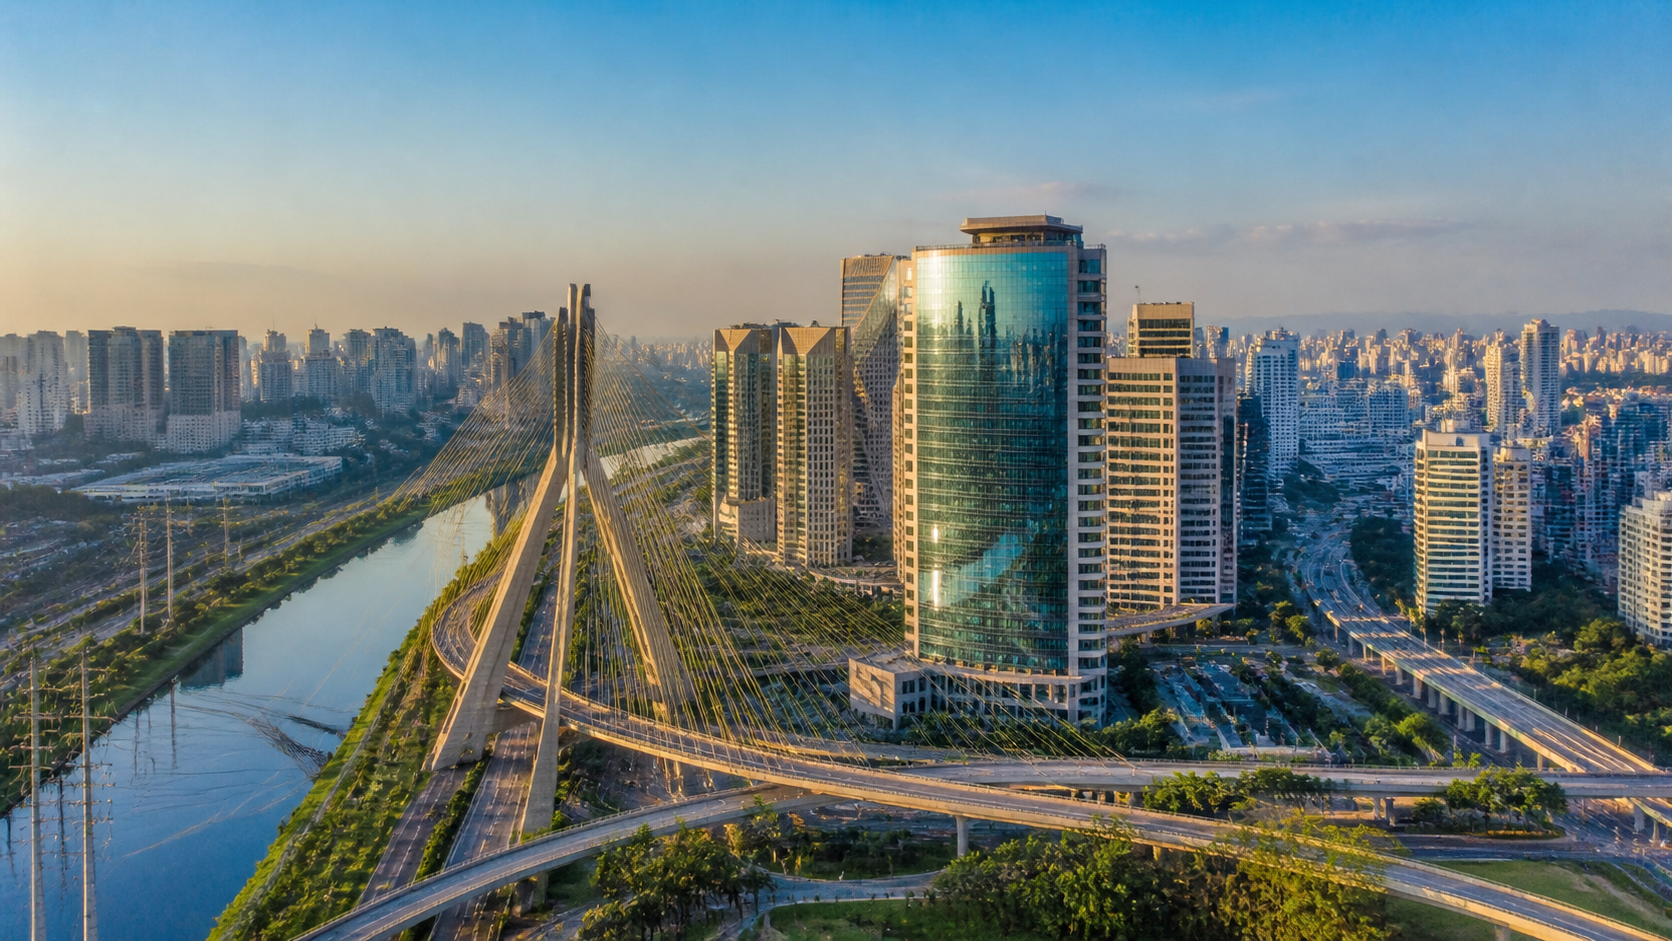
Cooling inflation and steadier currencies are unlocking a services boom.
Deloitte's industry outlook frames South America's leading economies in cautious but genuine optimism for H2 2026. As inflation gradually cools and exchange rates stabilize, retail, financial and insurance services are set to grow beyond 6% in key markets such as Colombia and its neighbors — a services expansion few emerging-market analysts anticipated.
The deeper story is diversification: commercial confidence is broadening beyond commodities into services and light manufacturing, laying a continuously stable foundation for the continent's recovery — and giving global investors a low-correlation growth pocket.
New development capital is financing the continent's own integration.
As the BRICS grouping expands, Africa is receiving a fresh wave of capital: local-currency infrastructure lending from the New Development Bank, smart-factory knowledge transfer, and green-energy investment tied to the continent's transition endowment. The pattern reduces hard-currency risk while funding the roads, grids and ports integration requires.
Just as important, African economies are pushing South–South trade — deep binding of crude, minerals and processed agricultural value chains with Asian and Latin American partners — so regional integration is accelerating on the continent's own terms.
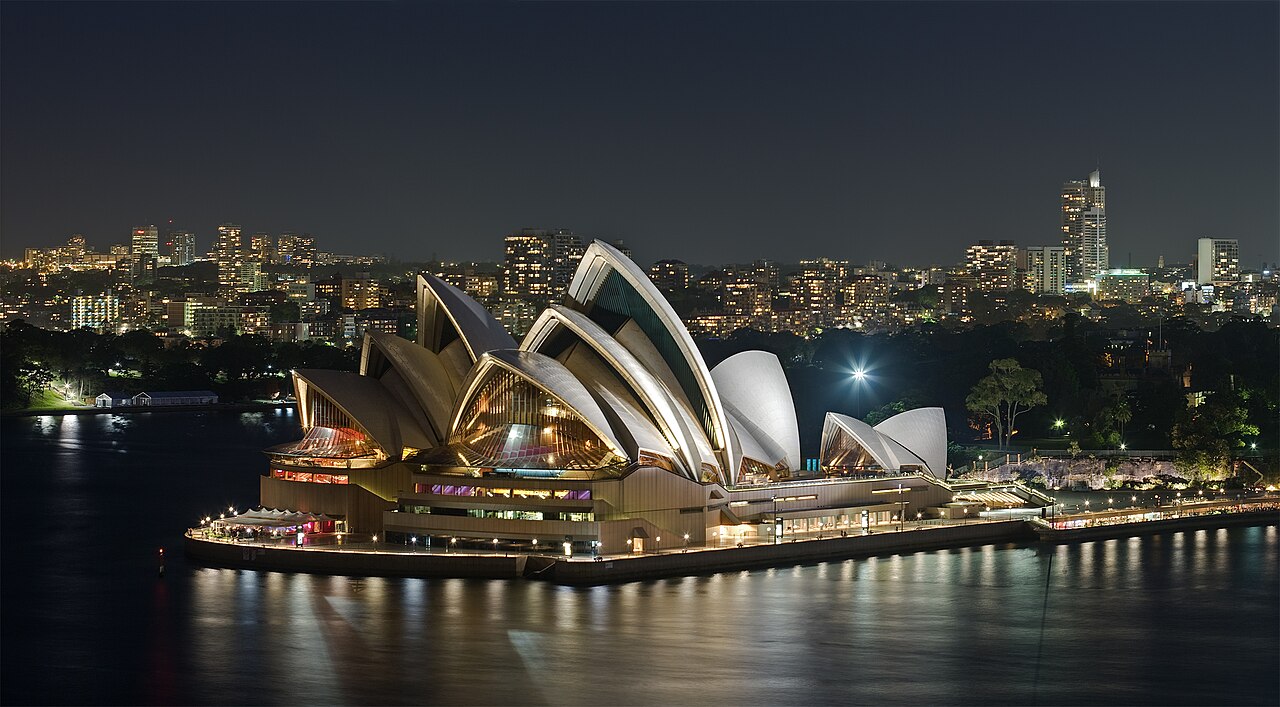
A rare economy collecting rent on both the old and the new world.
Australia and New Zealand enter H2 2026 with a dual buffer: commodity prices holding at elevated levels keep fiscal space wide for the resources complex, while the full rebound of cross-border tourism and international education across the Asia-Pacific is lifting service exports and current-account incomes at speed.
The combination — legacy-resource cash flow plus a services recovery — gives the region unusual resilience for an economy of its size, and makes it a quiet beneficiary of Asia's continued expansion.
In the H2 2026 investment map, artificial intelligence and the green transition are no longer parallel tracks. They are interleaved, mutually causal — and together they form the defining super-cycle of global capital. Data centers are doubling the world's appetite for power, and power is becoming the scarcest asset in technology.
From model experiments to value realization
Capital is rotating out of "large-model experiments" and into infrastructure foundations and commercial payoff. PwC projects $31.6 trillion of global AI-infrastructure capex by 2050 — and the short-term explosion point for data-center spending is exactly 2026.
AI's electricity appetite becomes energy's best customer
The core bottleneck of the green transition is grid absorption — and the AI boom just became its greatest catalyst. Data-center electricity demand is expected to double by 2030, turning reliable, clean baseload power into the decade's defining scarcity.
Strip away the noise and three structural forces explain nearly all of 2026's good news.
First-quarter global FDI soared 42% year-on-year, with the electronics and chip supply chain entering an explosive upcycle. Compute has become a tradable commodity, and the countries that host it are collecting the margin.
US · East Asia · ASEANBRICS expansion and thriving South–South trade are cutting the real cost of crossing borders: local-currency settlement and interconnected payment rails lower friction for everyone, redirecting flows toward Southeast Asia, Africa and Latin America.
ASEAN · Africa · LatAmMature green and intelligent technology — much of it exported at scale from Asia's manufacturing core — is slashing the friction cost of decarbonization for every importing economy, from the Gulf to the Balkans. The transition got cheaper right as compute made it urgent.
Energy importers · MENA · AfricaIn early September 2026, the World Trade Organization published its latest Goods Trade Barometer — and the reading caught almost every forecaster on the wrong foot.
Composite reading, September 2026 · Baseline = 100 · Above trend = expansion
The composite index climbed to 102.0, decisively above the 100 trendline — the formal signature of a "super-trend expansion" in world merchandise trade. Geopolitical friction has not stopped globalization; it has rerouted it. Multilateral trade is accelerating through new supply-chain corridors that bypass the old central artery, knitting together North America, Europe, Japan, Korea, Taiwan and Southeast Asia into a denser, more redundant lattice.
The composition of the rebound matters as much as its size. This is not a commodity story or a consumer-restocking story — it is a capital-equipment story. The goods crossing borders in record value are the physical ingredients of the AI economy: advanced chips, server racks, precision instruments and the power electronics that feed them. Trade and the technology cycle have fused into a single updraft.
The WTO's forward-looking composite signals continued above-trend momentum into early 2027.
Cross-border demand for electronic components and precision instruments is pushing air cargo to unprecedented utilization.
The single strongest driver of the rebound — AI compute infrastructure trade among the US, Japan, Korea, Europe and Taiwan.
Share of global greenfield investment value captured by US strategic sectors — chips, data centers, critical minerals.
S&P Global's monthly outlook shows US inflation pressure smoothly easing with core readings stable, sharply lowering the risk of further tightening in H2. The "interest-rate high pressure" over global capital markets has been phase-released. Meanwhile, chips-act and defense-tech spending are compounding: strategic US sectors — domestic semiconductor infrastructure, cutting-edge data centers, critical-mineral extraction — now capture 44% of global greenfield investment value.
Advanced packaging · Data-center grids · MineralsS&P's August–September outlook confirms Q2 real GDP across Western Europe and the euro area beat consensus broadly — driven by export rebound and, crucially, an unexpected revival in private consumption as tightening loosens its grip. Corporate Europe is re-arming its factories: small and mid-sized manufacturers are investing heavily in edge computing and flexible assembly lines, pushing smart-warehousing and high-end machine-tool procurement into an intensive ordering phase across Southern and Eastern Europe.
Smart warehousing · Machine tools · Edge retrofitWorld Data Lab's latest estimate: even excluding the anchor economy, emerging markets added nearly 110 million middle-class consumers in 2026 — concentrated in South Asia (India), Southeast Asia (Vietnam, Malaysia) and pockets of Latin America. And the green build-out financing this consumption is changing hands: as panel and battery costs collapse, private capital — independent power producers, affluent households — has become the main engine of low-carbon transition across Southeast Asia and Africa, with distributed grids and small-scale storage blooming.
FinTech · Distributed solar · Mini-grids| Region / Corridor | Core support | Sectors to watch |
|---|---|---|
| Global cross-border supply chains | WTO barometer above trend at 102.0; air-freight index at 102.8 and climbing | International air-cargo logistics, supply-chain diversification compliance software |
| North America | Inflation firmly cooling; strategic high-tech and infrastructure investment at a record 44% of global greenfield value | AI advanced-packaging materials, upstream semiconductor minerals processing, data-center grid infrastructure |
| Southeast & South Asia | 110 million new middle-class consumers; private green-energy investment turning decisively positive | Cross-border FinTech for Indonesia and Vietnam, distributed commercial solar integration |
| Europe | Q2 GDP broad beats on exports and consumption; factory re-equipment cycle underway | Smart warehousing, high-end machine tools, Southern/Eastern European automation relocation |
Beyond the headline indices, these are the industry-level opportunities institutional money is actually underwriting in H2 2026. Open any entry for the full briefing.
The physical layer of the AI boom is where the spending lands first. With AI server shipments up 55.9% in 2026 and the four largest US cloud groups lifting capex beyond 80%, demand for high-end IC substrates, advanced packaging capacity and high-speed interconnects is running far ahead of supply — pulling East Asian and American suppliers into multi-year order books.
Enterprise spending has pivoted from training experiments to large-scale inference and AI agents that actually execute work — automating financial analysis, clinical documentation and end-to-end supply-chain operations. This is the layer where AI's productivity promise converts into booked revenue, and venture dollars are following it downstream.
Europe's twin pursuit of digital sovereignty and carbon neutrality has made green data centers the continent's hottest sub-sector. US capital is funding local build-outs — over $40 billion destined for Portugal's sovereign-cloud AI hub — while liquid cooling (up to 50% energy savings), AI-driven utilization platforms and edge compute command premium venture pricing.
The strongest hard-asset demand of the cycle. Data-center load growth has strained North American grids and lifted power prices, while legacy networks hit absorption limits. Global storage demand is growing 60%+, lithium batteries enter a fresh cycle, and orders for transformers and high-voltage equipment are landing across the US faster than factories can quote them.
Round-the-clock compute cannot run on daylight alone. The US market is forming an integrated "baseload" investment basket — solar-plus-storage, nuclear, geothermal and natural gas together — as tech buyers sign for firm, always-on clean power. It marks the maturing of the energy transition from ideology to engineering.
A €682 billion program is turning the Mediterranean rim — Spain, Greece, Italy and Egypt — into the world's largest clean-power generation network, with an unprecedented wind-and-solar pipeline bound together by transnational interconnects. The strategic prize: breaking Europe's fossil-fuel dependence through geography rather than subsidy.
Global clean-hydrogen investment has cleared $130 billion, and Europe leads the world in project count with investment up 35% year-on-year. The near-term deployments are industrial decarbonization and heavy transport — steel, chemicals, shipping — where electrification reaches its physical limits.
Sovereign chip programs on both sides of the Atlantic are entering the equipment-installation and mass-production phase, exploding demand for ABF substrates, photoresists and advanced packaging materials sourced locally. Meanwhile, scarce and expensive labor is forcing factories toward embodied-AI robotics, AGVs and intelligent warehousing — penetration rates now sit at record highs.
Global digital trade keeps growing far faster than conventional trade. Hot sub-niches: modernized overseas warehousing, digital customs SaaS, and AI-driven cross-border supply-chain platforms. On the ground, Asia–Europe rail freight hit record volumes — the land bridge binding Asian manufacturing to European consumers has become the system's most stable anchor, and local-currency settlement keeps lowering its cost.
As the US and Europe push chips-act subsidies and supply-chain-security programs into their densest disbursement phase, AI and semiconductor infrastructure is undergoing a historic decentralization — and suppliers positioned outside the traditional central corridor are collecting a generational windfall.
The ABF bottleneck nobody can build fast enough
America and Europe are pouring concrete into new wafer fabs — but fabs without advanced packaging are engines without gearboxes. Capacity for leading-edge packaging such as CoWoS-class processes remains critically short, and that shortage radiates demand straight up the materials chain.
When racks outrun air, water gets the contract
Latest-generation AI accelerators have pushed per-chip power draws so high that traditional air cooling simply cannot cope. Every new AI data center in the West is now specified around direct liquid cooling, high-density power distribution and precision thermal control — a specification shift that rewrites the vendor list overnight.
The multi-year "transformer famine"
AI data centers are draining Western grid headroom, and the grid itself — transformers, high-voltage switchgear, transmission hardware — faces a shortage measured in years, not months. Lead times for large power transformers have stretched into the middle of the decade, and every new data-center campus needs a small substation of its own.
Forecasts as published by the IMF and cited institutions for 2026. Europe's upgrade is directional (+0.4pp for the euro area and Western Europe per S&P Global); Germany's growth landed at nearly double prior forecasts on net exports. South America's services complex — retail, finance and insurance — grows beyond 6% in key markets per Deloitte's outlook.
A new middle class the size of a continent is forming across South Asia, Southeast Asia and Latin America — and Southeast Asian governments are competing head-to-head to host the factories, data centers and treasury hubs that will serve it.
World Data Lab's newest projections show emerging markets — excluding the world's anchor economy — still adding nearly 110 million middle-class consumers in 2026. The purchasing power is clustering in South Asia (India), Southeast Asia (Vietnam, Malaysia, Indonesia) and parts of Latin America. Just as important is who funds the infrastructure underneath them: with solar and battery costs in freefall, private capital — independent power producers and even affluent households — has displaced government subsidy as the main engine of the low-carbon transition across Southeast Asia and Africa. Distributed grids and small-scale storage are flowering at street level, not just in national plans.
APAC HQ & Digital Hub
The region's "super-brain" for multinational capital allocation — now competing on brains, not just stability.
Chip OSAT & Electronics Manufacturing
Hanoi's new semiconductor-industry strategy is the most aggressive incentive package in the region.
Green Batteries & Critical Minerals
Jakarta doubles down on resource localization — with sharper carve-outs to attract non-traditional partners.
High value, high urgency
The sharpest rebound is in chips, AI server hardware and precision medical instruments — assets that fly, always. Charter freight margins are expanding fast on US–Mexico, Japan–Korea–Taiwan–US and Europe–US lanes for FedEx, UPS and DHL.
The fragment dividend
Fragmented supply chains mean recomputing tariffs, origin certifications and carbon-border compliance across dozens of jurisdictions. Platforms for supply-chain visibility, smart customs and multi-currency settlement — Flexport in the West, Southeast Asia's digital-logistics unicorns at home — are in breakout growth.
Mexico for the US, Eastern Europe for the EU
Mexico sits beside US assembly; Poland and Romania beside EU consumption. Local warehouse estates — logistics REITs such as Prologis — and cross-border truck-and-rail intermodal operators hold the strongest pricing power of the entire trade recovery.
Optimism with eyes open: the two structural frictions every reader should track into 2027.
The US and Europe are tightening tariffs and local-content rules on solar modules, EVs and grid-critical components such as transformer parts. The policy protects domestic manufacturing — but it is raising procurement costs across the global green transition and slowing deployment at the margin.
What to watch: the spread between localized and imported component costs; commissioning timelines for utility-scale projects in tariffed markets.
Technology groups are expanding compute aggressively while facing stricter ESG regimes — including Europe's solvency-linked directives. Reconciling exponential compute demand with hard emissions indicators is now the structural bargaining table of Western markets, and power-purchase strategy has become a board-level discipline.
What to watch: clean-baseload contracting volumes; the premium commanded by low-carbon compute capacity.
"Every generation gets one synchronized moment when the map redraws itself — when technology, trade and money all change direction at once. 2026 is that moment. The continents profiled in this edition are not waiting for certainty; they are compounding through it."
— The Meridian Editorial Desk · Geneva · Singapore · New York